
What would WellthCare mean for your company?
A few quick answers, your results in seconds. No disruption to your current plan.
Start with a few quick answers
Enough to show what WellthCare would be worth to your team.
10 to 5,000. Values outside this range are brought inside it when you leave the field.
From $25,000 to $120,000 a year. You can type freely — limits apply when you leave the field.
Healthcare that pays you back.
The first Health-to-Wealth™ Benefit System: preventive care that pays your people back with $0-co-pay visits, earned Store reward dollars, and automatic retirement contributions, at zero net cost to you and no change to the plan you already have.
- Patent-pending
- ERISA-reviewed by counsel
- With or without major medical
The squeeze runs both ways
Employers
Premiums climb, wages climb, turnover stays brutal. BUCA-grade benefits, meaning Blue Cross, UnitedHealth, Cigna, and Aetna, stay out of reach.
Employees
The same squeeze from the inside. A high deductible pushes care later, and the year ends with nothing saved.
80% of physicians say patients often or sometimes delay or refuse care because of cost concerns. 79% say high deductibles are a key driver of those concerns.
How it works
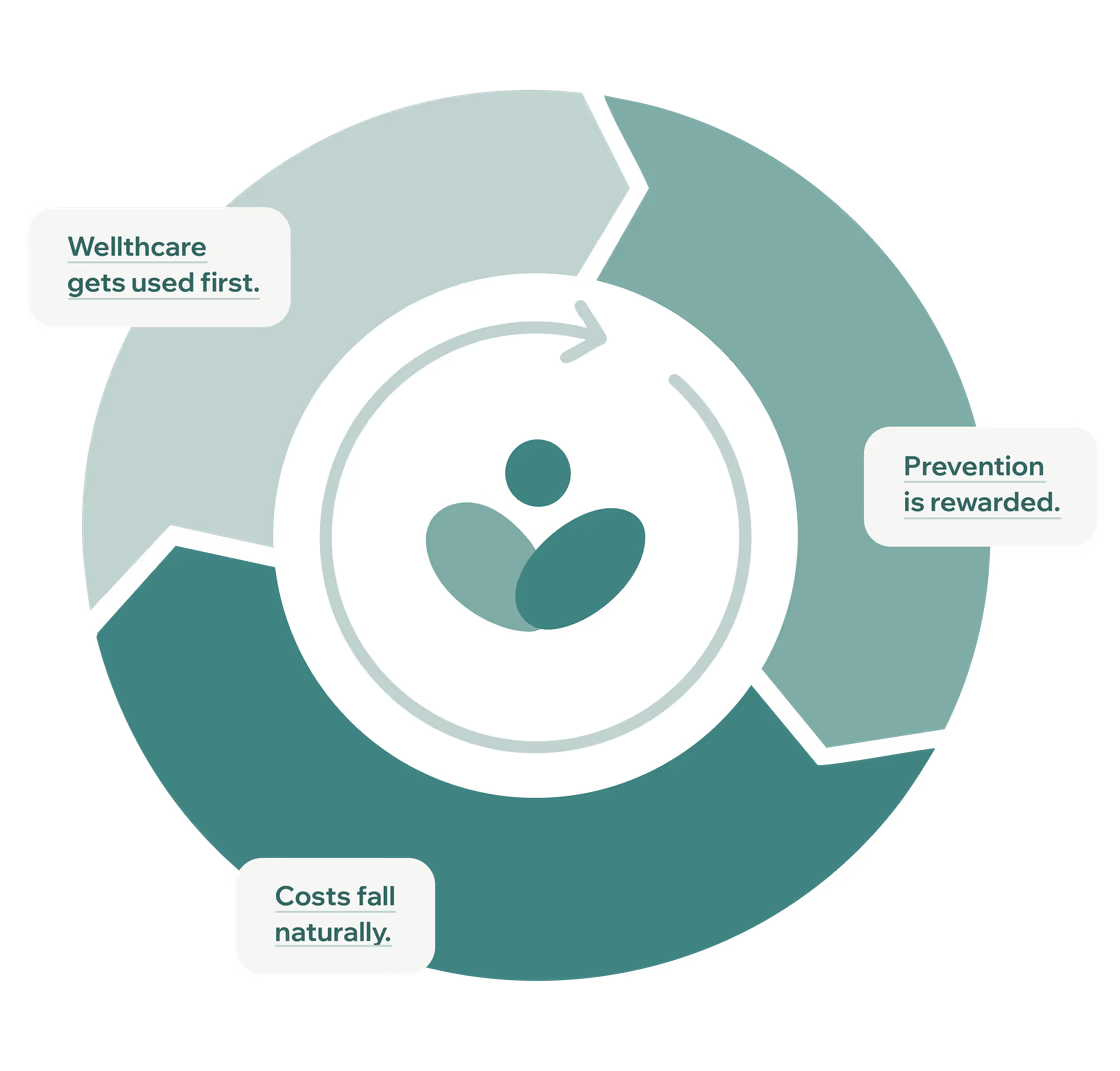
WellthCare works alongside your existing health plan and gets used first. Employees get $0-co-pay care, earn reward dollars at the WellthCare Store, and build their retirement automatically. Employers see fewer claims, lower costs, and higher retention, with no disruption.
Care
$0 co-pay care, used first
Everyday care runs through WellthCare before it reaches your existing plan. Savings your people notice immediately.
Store
Reward dollars at the WellthCare Store™
7,000+ eligible health and wellness products, funded by the reward dollars they earn for verified preventive actions. Balances roll over and are never forfeited.
Retirement
Automatic retirement contributions
Deposited automatically, no employee action needed. Savings that build whether or not anyone opts in.
Two employer realities. One system for both.
Whichever one you are, nothing about your current plan has to change.
Without major medical
When carrier pricing is out of reach
Real healthcare and retirement benefits your team will actually use, without a BUCA cost structure.
- $0-co-pay, $0-deductible urgent care, primary care, Rx, labs, and mental health
- Automatic retirement contributions
- Store dollars earned for verified preventive care
With major medical
When premiums keep climbing
WellthCare runs alongside your plan and gets used first, so a high deductible stops pushing care later and more expensive.
- Fewer claims reaching the plan you already pay for
- Less waste, healthier employees, better retention
- Readiness Index™ data showing whether and when a plan change makes sense
What’s included
Most programs in this space stop at access: a virtual doctor and a discount card. WellthCare adds a formal plan of care, concierge follow-through, earned Store dollars, and a separate retirement contribution.
- Unlimited virtual primary care, with a Care Concierge who arranges whatever the doctor orders
- 24/7 virtual urgent care, plus up to 6 in-person visits a year at $200 each
- 1,000+ covered lab tests at $0 across 2,200+ Quest locations through QuestSelect
- Eligible preventive screenings and immunizations at $0
- 1,200+ common generic prescriptions free, up to 80% off outside the formulary
- Mental-health tele-counseling, any hour, for employees and their families
- WellthCare Navigation™: cost and quality compared before any planned procedure
- WellthCare BillReducer™: line-by-line bill review, averaging 70% off eligible bills
AI-assisted plans of care are reviewed by a nurse practitioner and a physician. Coverage differs by benefit: labs and prescriptions are employee benefits, and the rest extend to a spouse and children. Benefits and eligibility vary by plan design and governing documents.
What it’s worth to your people
Per year. Healthcare savings are per household; the rest are per employee.
$5,000–$8,000
estimated household savings on common healthcare costs
$1,260
estimated Store rewards earned
Up to $1,100
in automatic retirement contributions
Plus $0-co-pay primary, urgent, and mental health care for employees, their spouse, and their children, $0 prescriptions and lab work for the employee, and bill review that saves an average of 70% on eligible medical bills.
Plus about 20 hours a year back per employee, from care that does not need a waiting room.
Benefits and eligibility vary by plan design and governing documents. Store rewards are estimated at $105 per eligible employee per month, a forward projection rather than a measured average.
The calculator above counts Store and retirement value only. Out-of-pocket savings sit on top of it. Ranges are typical outcomes, not guarantees.
Employers encouraged to review with own counsel. Results depend on plan operation.
Why employers say yes
Fewer claims
Employees use their $0 deductible WellthCare benefits first, so fewer claims reach your health plan over time.
Lower costs
Employer payroll taxes typically drop. Employee take-home pay stays about the same.
Higher retention
Better care. Lower claims. Higher retention. A benefit people can feel in the same month they earn it.
I love getting a quick health check, and it earns me store & retirement rewards.
TeddyWellthCare Member
I’ve never been able to put much away for retirement. Knowing that taking care of my health is also helping me build something for my future means a lot.
JasonWellthCare Member
They reduced my bill from over $5,000 to $400.
LydiaWellthCare Member
Individual member experiences; results vary.
The engine underneath
Patent-pending, automated, and audit-ready. Employees complete two 40-second scans a month to stay eligible; nobody at your company administers any of it.
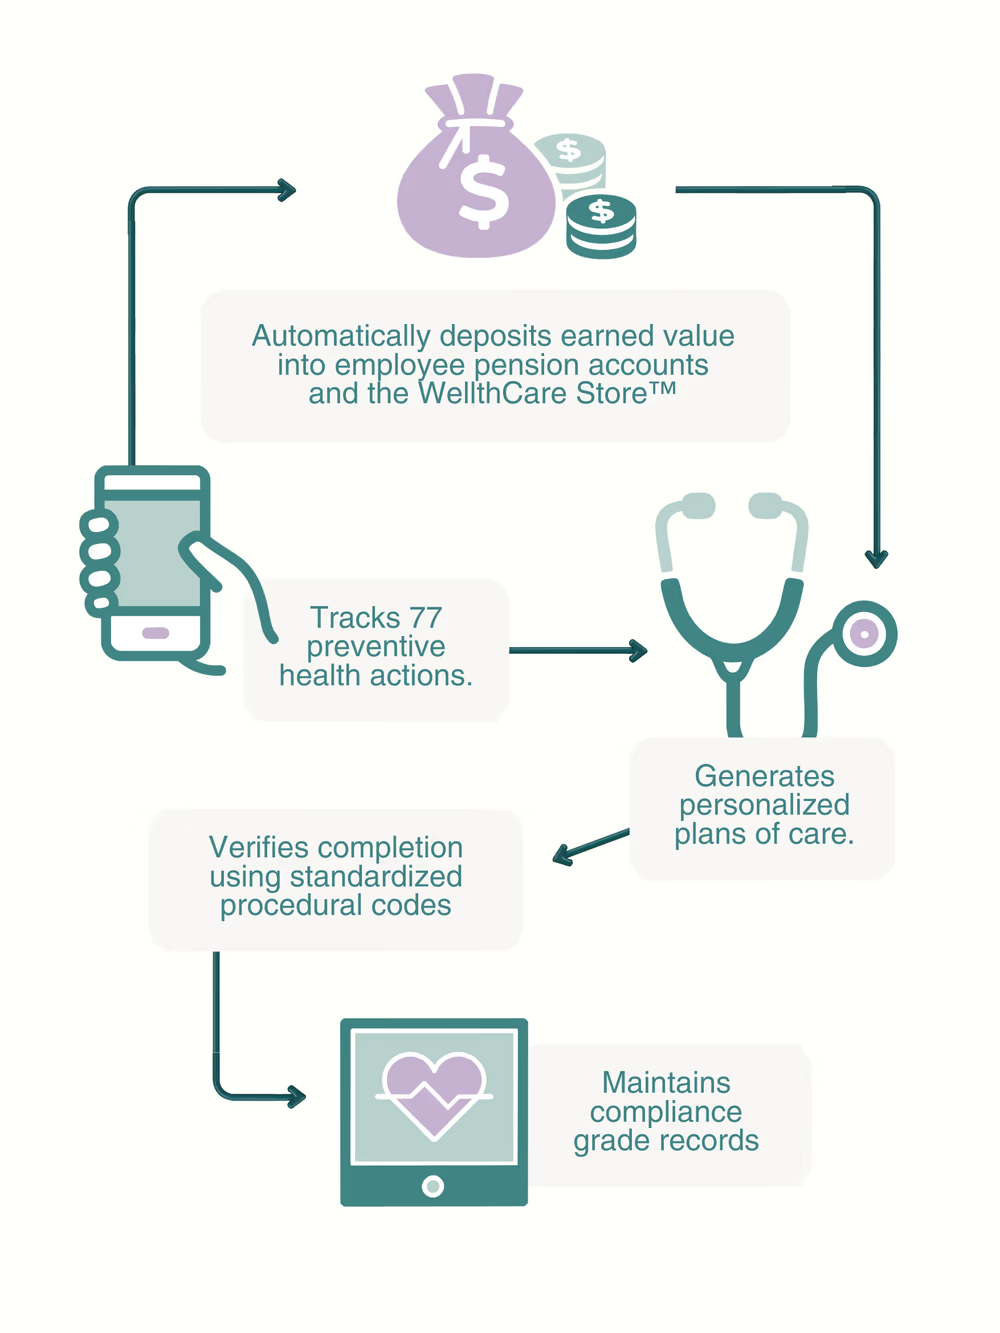
- Tracks 77+ verified preventive actions
- Maps each one to standardized preventive care codes
- Keeps audit-ready compliance records
- Funds each employee’s retirement account, Store balance, and $0-cost care eligibility automatically
Rewards, reporting, and regulatory tracking run in real time. Your HR team keeps its calendar; we handle care and billing questions.
Nothing is sold on promises. Everything is sold on proof.
Structured, not improvised
A self-insured supplemental medical plan under IRC §§125, 105, 106, and 213(d), operating within ERISA, HIPAA, and ACA requirements.
Opinions on file
Three independent legal opinions support the structure, shareable under NDA. Not summarized: the actual documents.
Legal support services
Protection of up to $500,000 for the employer and $10,000 per participant, because a structure worth adopting is a structure worth defending.
Clear eligibility
W-2 employees enrolled in the employer's Section 125 plan. Owners, partners, self-employed individuals, and >2% S-corp shareholders are not eligible.
Your advisors will have questions. Good. Bring them.
It starts here. It doesn’t stop here.
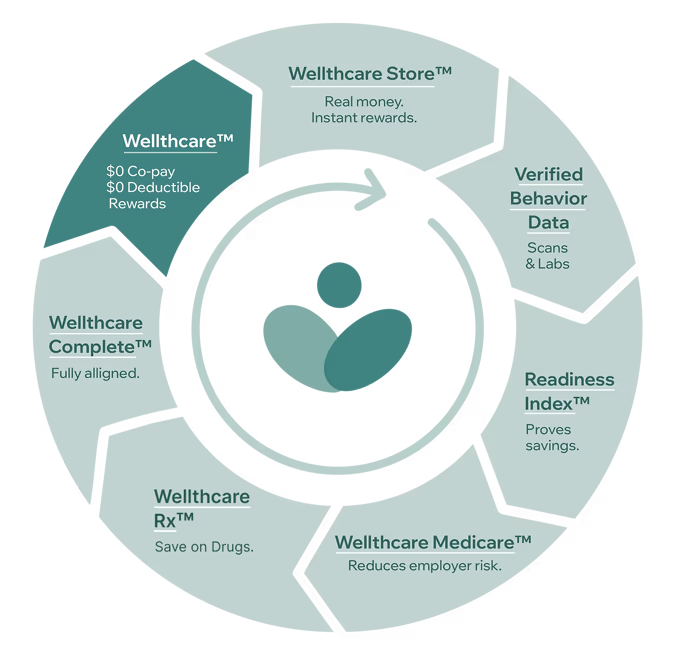
WellthCare begins as a zero-net-cost add-on. Everything after it is optional, and earned by your own data rather than by pressure.
WellthCare Store™
Real, spendable dollars earned for verified preventive actions. Balances roll over year to year and are never forfeited.
WellthCare Readiness Index™
Turns actual usage into a report on what your current plan is costing you.
WellthCare Rx™
Transparent pass-through pricing in place of an opaque pharmacy benefit manager (PBM), typically 20–40% below traditional PBM cost.
WellthCare Medicare™
Keeps Medicare-eligible employees in-system and off the group plan.
WellthCare Complete™
A self-funded alternative to your current plan, with projected savings of 30–45%, if and when your own data says so.
No assumptions and no pressure. Just clarity at renewal.
Questions a CFO would ask
Is this insurance?
No. Not insurance, not a wellness program, not an HMO, not a perk. It is a benefit system that works alongside the health plan you already offer, and your plan stays exactly as it is.
What does it cost the employer?
It is structured as a zero-net-cost add-on, funded through the tax efficiency created inside your existing Section 125 plan, so the employer contribution is offset rather than added. Your advisors will want to walk that through line by line. That is the expected outcome, not an obstacle.
Does it replace our current plan?
No. No disruption, no change of carrier, no re-enrolment. WellthCare simply gets used first for everyday care, which is precisely what reduces the claims reaching your existing plan.
Is this compliant?
It is structured as a self-insured supplemental medical plan under IRC §§125, 105, 106, and 213(d), operating within ERISA, HIPAA, and ACA requirements. Three independent legal opinions support the structure and are shareable under NDA, and legal support services protection is in place. Bring your own counsel. The structure is built to be examined.
Who's eligible?
W-2 employees enrolled in the employer's Section 125 plan. Owners, partners, self-employed individuals, and more-than-2% S-corporation shareholders are not eligible.
Does employee take-home pay change?
Take-home pay stays about the same. The tax efficiency inside the Section 125 plan does the work, so employees gain Store dollars and automatic retirement contributions without watching their paycheck shrink.
Do we have to adopt the rest of the ecosystem?
No. WellthCare works on its own indefinitely. The Readiness Index™ reports what your own utilisation data shows, and whether to act on it is your call: at renewal, or never.
What's the catch?
Fair question, and now is the right time to ask it. The incentives line up: when preventive care is used first, claims against your existing plan fall, and the economics that creates fund employee value. There is no separate pot of money and nothing hidden in the mechanics. Every claim on this page is documented, and the opinions behind it are available under NDA.
Put your company on a WellthCare Plan.
Thirty minutes, your own numbers, and every document your advisors will want to see.
- 30-minute call
- Personalized retirement & Store projections
- No disruption to your current plan